NPS & Retirement Investing
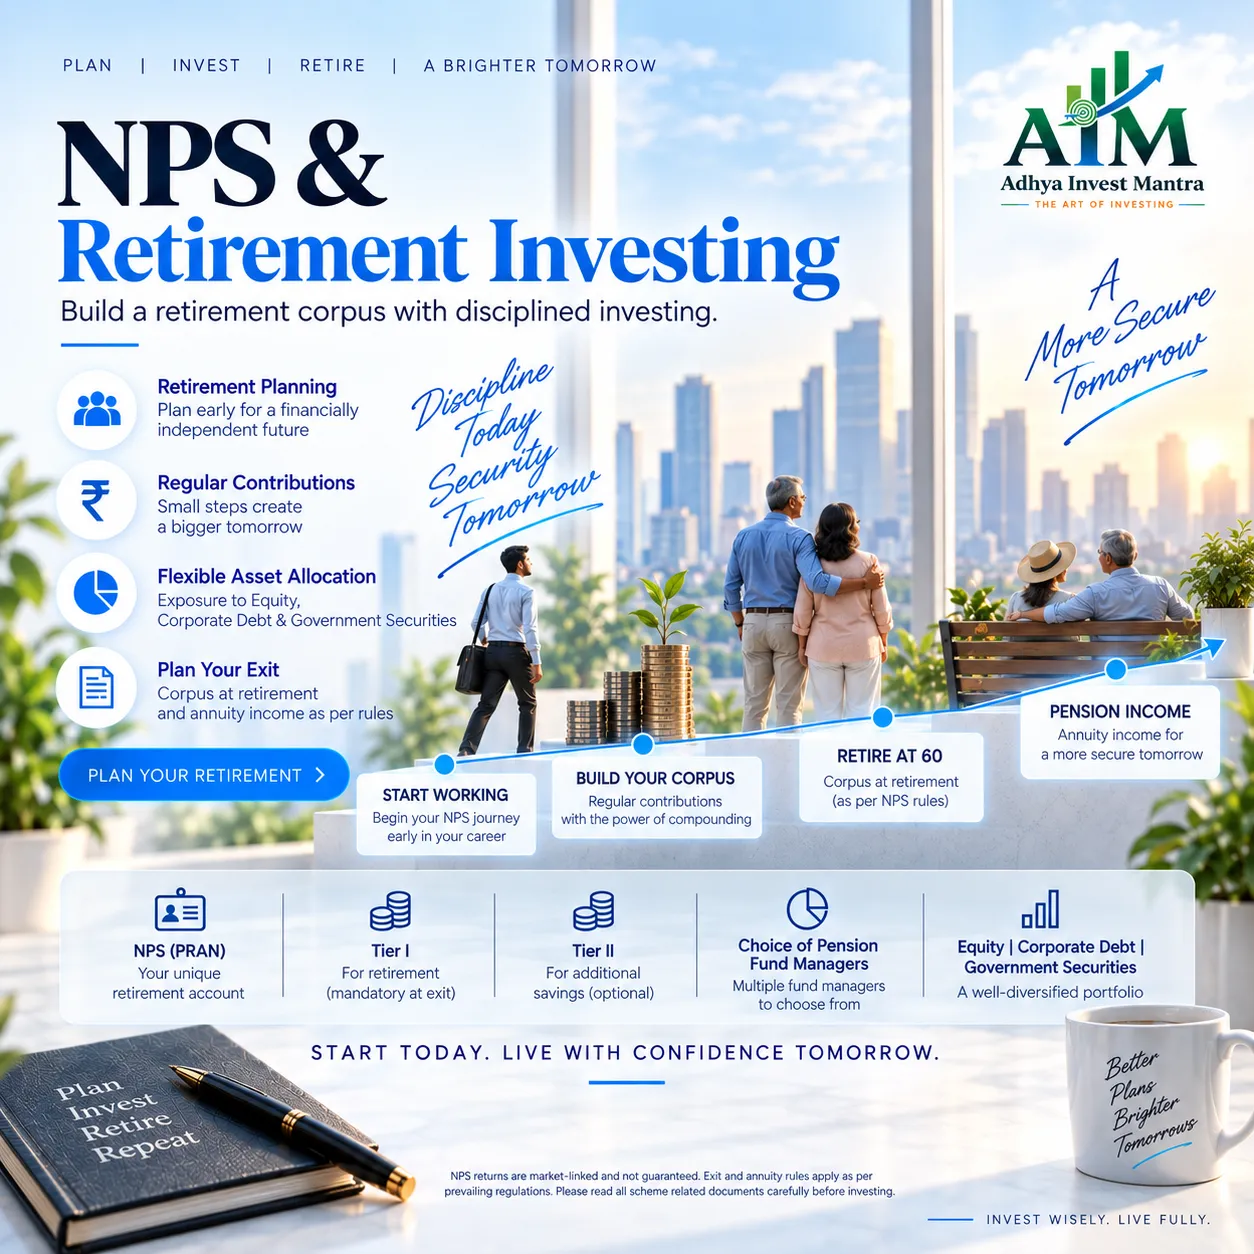
Build a pension corpus while you earn through the National Pension System, then draw an income from it after 60 — with the exit rules explained before you start.
Who this suits
Anyone without an employer pension, looking for an additional Section 80CCD(1B) deduction, or starting a retirement corpus from scratch.
What's included
- Tier I and Tier II NPS accounts opened online through a KRA-linked process
- Additional deduction of up to ₹50,000 under Section 80CCD(1B), over and above the 80C limit
- Choice of Pension Fund Manager and equity/debt/government-security allocation, explained before you pick
- Clarity on the exit rules: partial withdrawal conditions, and the mandatory annuity portion at retirement
How it works
Open Tier I (and Tier II, optional)
A KRA-linked, mostly online process using PAN and Aadhaar; a Permanent Retirement Account Number (PRAN) is issued.
Choose your Pension Fund Manager
And your split across equity, corporate debt and government securities — explained before you pick.
Contribute regularly
Lump sum top-ups or a SIP-style recurring contribution, whichever fits your cash flow.
Plan the exit
At 60, up to 60% comes out as a tax-free lump sum; the rest buys an annuity for a monthly pension.
Frequently asked
Q.Can I change my Pension Fund Manager later?
Yes, PFM changes are permitted once a year through the NPS online portal.
Q.Can I withdraw before 60?
Partial withdrawal (up to 25% of your own contributions) is allowed after 3 years, for specific reasons like a child's education, medical treatment or a home purchase, limited to 3 withdrawals over your tenure.
Q.How is the maturity amount taxed?
The 60% lump sum withdrawn at 60 is currently tax-exempt. The annuity purchased with the remaining 40% is itself tax-free at purchase, but the monthly pension you receive from it is taxed as income in the year you receive it.
Q.How is this different from an employer's NPS contribution?
The mechanics are identical; an individual (Tier I) account is one you open and fund yourself, in addition to or instead of any employer NPS contribution under a corporate model.